- A resolution to the Mid-east conflict has become more elusive and complex, shifting the forecast towards higher oil prices and bond yields. However, these headwinds have not taken the wind out of the sails of the global economy.
- The U.S. Federal Reserve has raised interest rates for the first time in three years to combat inflation that has proven quite sticky alongside a solid U. S. economic outlook. It would be unconventional for it to be the last. We expect a second increase in the fourth quarter to keep longer-term inflation expectations anchored.
- By comparison, we believe the market is overplaying its hand in pricing several and imminent rate hikes by the Bank of Canada. Inflation is not in the spectrum of its U.S. counterpart, nor does it have the same drivers. Coupled with a worsening trade conflict, dampened sentiment, and only modest growth expectations, the dynamics press against a follow-the-leader central bank response.
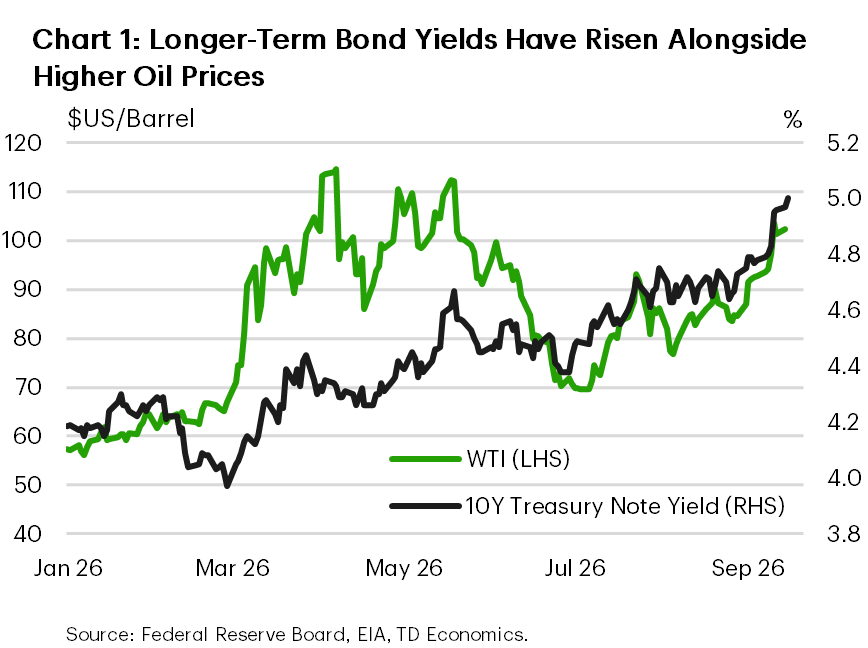
The summer has seen a twister of conflicts, from escalation in the Mid-east to Canada and the U.S.’s escalating tariff dispute. At this point, neither look to have an off-ramp in the near future, causing us to raise the forecast for oil prices (see table). Bond yields have risen sharply alongside oil prices as markets price in higher inflation and a greater degree of central bank tightening globally (Chart 1). Most major central banks now have a tightening bias. The ECB, the Bank of Japan and U.S. Federal Reserve have already raised rates this quarter and some of them are likely to do so again this year. However, it’s reasonable to expect the Bank of Canada to stand pat. Tighter financial conditions have been imported via bond yields into Canada, the job market reflects slack, and the near-term impacts of trade escalation is unquestionably negative until more offsetting domestic investment drivers can kick in.
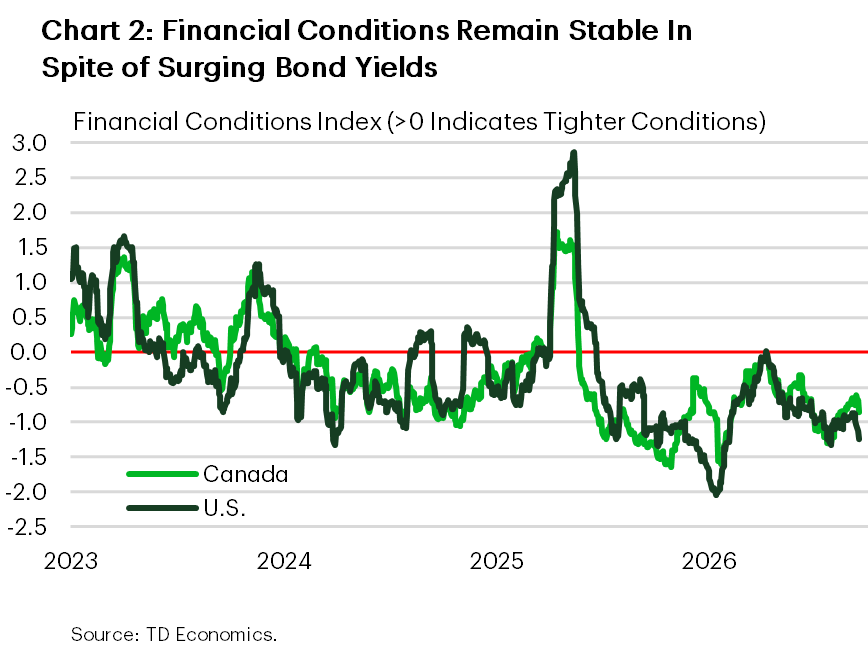
Despite the geopolitical doom and gloom, the U.S. economy continues to bravely follow the yellow brick road of AI investment to a peer-leading economic growth outlook. This investment boom is unlikely to be undercut by higher yields, especially given the ongoing resilience in overall financial conditions (Chart 2).
The global economy’s performance over the past quarter has been uneven but encouraging. On economic growth, Asian economies have continued to expand at exceptional rates, supported by AI-related capital expenditure—most notably in Taiwan, Korea, and Singapore and, to a lesser extent, in Japan. Many economies have maintained solid domestic momentum despite substantial exposure to the oil supply shock, with India chief among them. Some cracks are appearing within China, where growth is on track to land near the bottom of the authorities’ target range, and perhaps lower. The Eurozone has been surprisingly resilient, significantly outperforming in the second quarter. Behind this narrative lies a big growth-push from Ireland’s inherently volatile exports from large multinational corporations. However, looking past this, we expect the eurozone to grow at a near-trend pace this year and in 2027. Overall, despite oil prices trending higher than expected at the start of the conflict in February, the global economy has proven resilient.
Fed hikes amid higher oil prices and stalling inflation progress
It’s been a turbulent summer. Long Treasury yields hit a 19-year high, diesel prices ventured into record territory, and oil prices have yet to find stability amid escalation in the Middle East conflict and a pivot towards a communications shake-up at the Federal Reserve. Adding to the volatility, the U.S. Treasury Department announced that it would triple its long-duration Treasury buybacks to $6 billion to improve liquidity and cool the bond market. However, investors looked through the announcement, with renewed focus on fiscal sustainability concerns – a key factor pushing up long-end yields in recent months. As a result, yields are higher than before the program announcement by Secretary Bessent on August 19.
It’s too early for the rise in yields to leave a meaningful mark on the American economy. However, a higher yield forecast will ripple through the economy with time, leading us to downgrade the outlook for residential investment and trim household spending in H1-27. This still does not undermine the broader picture of resilience. Real GDP growth is tracking 2.8% in Q3, with momentum likely to carry into Q4. On balance, this leaves 2026 annual average growth at 2.2%, with 2027 also likely to be just north of 2%. The mid-term elections are unlikely to affect the outlook. Congress has already been a barrier to many parts of the President’s agenda that involve “the purse”, and we expect that situation to continue after the midterms.
Beneath the headline numbers, AI investment continues to account for an outsized share of economic growth. With hyperscalers rapidly tapping debt markets and making sizable investment commitments for next year, that tailwind is unlikely to fade anytime soon. But beyond AI, there are also encouraging signs that business investment is broadening into more traditional areas, like transportation and industrial equipment. Both posted sharp double-digit gains in Q2. Commercial and industrial loan growth is running at its fastest pace in four years, and nearly one in four small businesses report plans to increase capital expenditure over the next three to six months – a multiyear high.
The consumer has also remained a source of surprise and resilience. Q2 spending rose by an impressive 3.4% while Q3 is tracking only a modest deceleration to 3.0%. However, the headwinds to sustaining this momentum are building as the support from tax refunds fades alongside soft real income growth and a low household savings rate.
Fortunately, the job market remains a pillar of support to consumer spending. Job growth has averaged 71k over the three months through August, or slightly above the breakeven rate. Importantly, the breadth of hiring has widened, with more cyclically sensitive sectors, like manufacturing, construction, leisure & hospitality and retail trade all contributing. However, the U.S. is not on the cusp of a new “breakout” in employer demand. Job openings are low amid the sharp pullback in labor supply, The status quo of “low hire, low fire” remains the prevailing narrative.
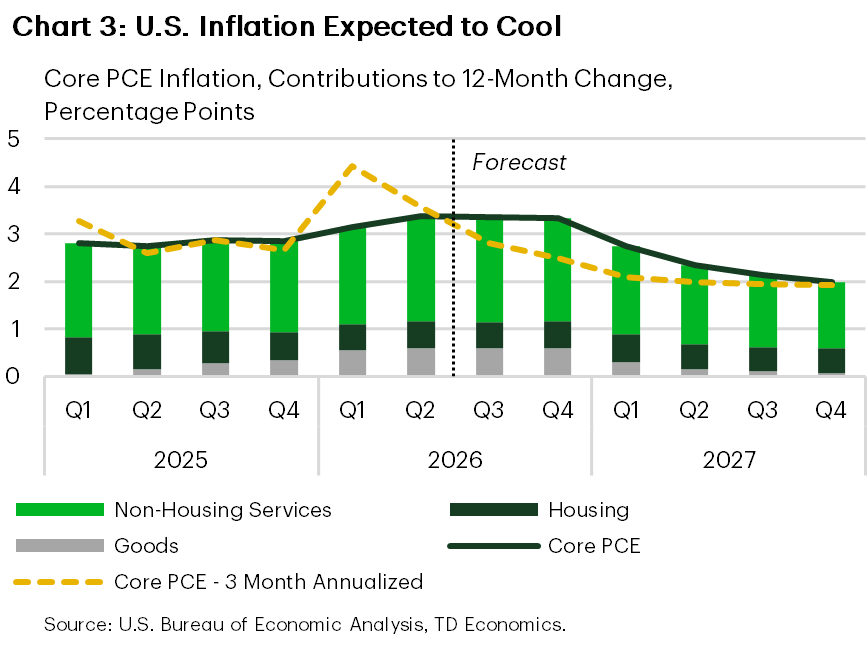
From the Fed’s perspective, the more pivotal development has been on the inflation front. Reaccelerating price pressures in August, combined with rising oil prices, have forced the FOMC’s hand. Failing to act would have led to an even sharper steepening of the yield curve. We think the Fed is likely to follow up with another quarter-point hike simply because a “one and done” approach would be viewed as inconsequential to markets and likely not succeed in providing reassurance on its commitment to return price stability. Back-to-back hikes would largely reverse last year’s “insurance cuts” and leave policy modestly more restrictive. Barring further unexpected shocks, the additional tightening should be sufficient to guide lower inflation through 2027 (Chart 3), paving the way for a few rate cuts.
Canada’s Economy Defiant To Trade Uncertainty
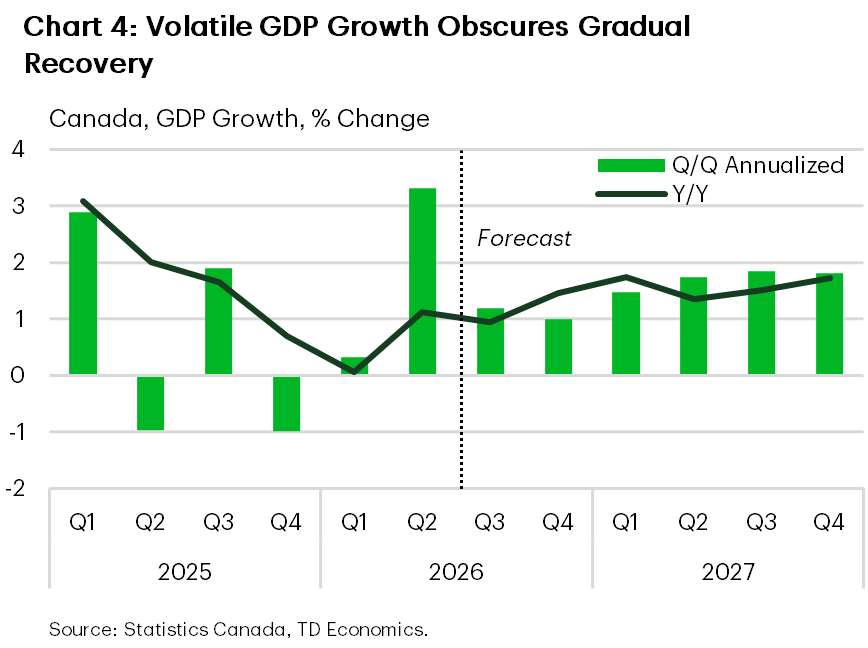
Recession chatter has quieted due to an upward revision to economic growth in Q1 but, unfortunately, trade uncertainty has not. New U.S. tariffs on 5% of exports south of the border, and Canadian counter-tariffs have taken effect – a stark reminder that businesses stand on porous ground (see commentary). So, while it is unambiguously good news that growth in the first half of the year was twice as strong as we had predicted in June, a return to a more pedestrian expansion is likely to unfold in the second half of the year. This year will still register soft 0.9% real GDP growth before modestly improving to 1.5% in 2027 and 1.8% in 2028, little changed from our June forecast (Chart 4).
This is one key underpinning on why we believe the Bank of Canada is not in an optimal position to raise rates, despite high oil prices that cut two ways: lifting energy-producing regions’ activity but also lifting inflation country-wide. This is counter to markets, which have priced several rate hikes through next year. Unlike its U.S. counterpart (see report), a broad swath of core inflation measures in Canada are still anchored at its target because of more pervasive trade uncertainty, economic slack and less demand-push inflation dynamics from AI supply chains.
In contrast, market pricing is reacting to the here-and-now, that we doubt will overwhelm other fundamentals: high oil prices and a sturdy labour market. No doubt, the latter is a bright spot, with the unemployment rate at 6.4% in August and an impressive 0.7 percentage points below last summer. But even with all that, the labour market is soft rather than healthy. In recent months improvements have become increasingly regionalized, with Alberta’s gain of 42k full-time jobs since December offset by declines in Quebec (-51k). This regional divide is expected to persist as new tariffs take effect, limiting the economic upside from higher energy prices.
A key challenge for Canada is to rotate demand slowly towards greater investment drivers, to push against the capital destruction that is flowing through the long tentacles of trade risks. There is immense potential to succeed, which we highlight via an investment supercycle over the next decade (see report). Although higher yields and energy costs create an obstacle in an already tenuous global risk environment, a focus on domestic policy shifts can offer a counterinfluence. For instance, the Federal Government recently announced new policies on the tax side to help increase the attractiveness of capital investments (see commentary). The potential investment boost from these initiatives is not yet included in our forecast, presenting an upside risk to the investment outlook.
Consumers have been spending at a healthy clip so far this year, likely buoyed by more generous government transfers and wealth gains, but we expect spending to slow through the end of this year and into early next year as purchasing power is crimped by higher energy costs. Higher government bond yields globally have pulled Canadian yields along for the ride, causing an upward shift in our forecast for government bond yields. This additional weight on the housing market will further limit the degree of rebound and economic support flowing through this sector over the next several quarters.
As for CUSMA, the risk environment has worsened since our forecast in June. Although we assume the status quo persists in the baseline forecast, it’s a double-edged risk on both the downside (more escalation) and upside (a trade agreement). From our lens, the risks from trade, economic growth, and oil prices should keep the BoC firmly on the sidelines. Although the prospect of an investment supercycle could become Canada’s economic superpower with time, we suspect the BoC will need to see convincing evidence of its sustainability as a key growth driver for the broader economy to offset the risks and weights elsewhere.
Forecast Tables |
|---|
| Interest Rate Outlook |
| Foreign Exchange Outlook |
| Commodity Price Outlook |
| Canadian Economic Outlook |
| U.S. Economic Outlook |
| Economic Indicators: G7 and Europe |
| Global Economic Outlook |
For any media enquiries please contact Oriana Kobelak at 416-982-8061
Disclaimer
This report is provided by TD Economics. It is for informational and educational purposes only as of the date of writing, and may not be appropriate for other purposes. The views and opinions expressed may change at any time based on market or other conditions and may not come to pass. This material is not intended to be relied upon as investment advice or recommendations, does not constitute a solicitation to buy or sell securities and should not be considered specific legal, investment or tax advice. The report does not provide material information about the business and affairs of TD Bank Group and the members of TD Economics are not spokespersons for TD Bank Group with respect to its business and affairs. The information contained in this report has been drawn from sources believed to be reliable, but is not guaranteed to be accurate or complete. This report contains economic analysis and views, including about future economic and financial markets performance. These are based on certain assumptions and other factors, and are subject to inherent risks and uncertainties. The actual outcome may be materially different. The Toronto-Dominion Bank and its affiliates and related entities that comprise the TD Bank Group are not liable for any errors or omissions in the information, analysis or views contained in this report, or for any loss or damage suffered.